

Instacart Shopper Rewards
by Branch Messenger
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
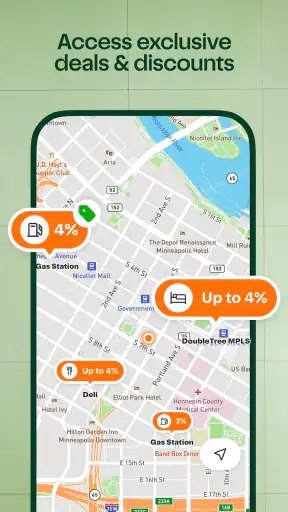
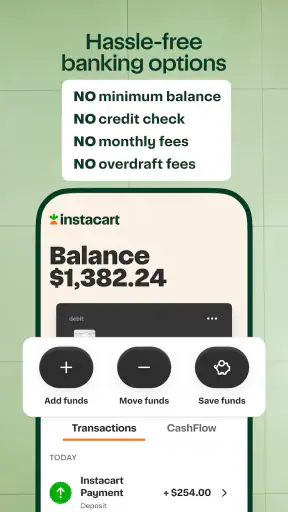
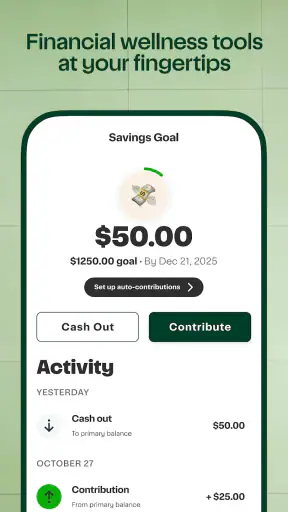
 Analysis by Getfullapps
I approached Instacart Shopper Rewards as a finance app rather than a general shopping tool, and that distinction matters from the first screen. Its focus is the debit card experience connected with Instacart Shopper, so the useful question is not whether it replaces a full banking app. The better question is whether it can make money management more convenient for people who already work through that ecosystem.
My overall impression is cautiously positive. The app is free, aimed at everyone, and published by Branch Messenger. It has reached over one hundred thousand installs, with a 4.3 average from more than five hundred ratings. Those figures suggest that it has found a real audience, although they do not tell me whether every shopper will find the workflow equally comfortable.
How the app feels during everyday money tasks
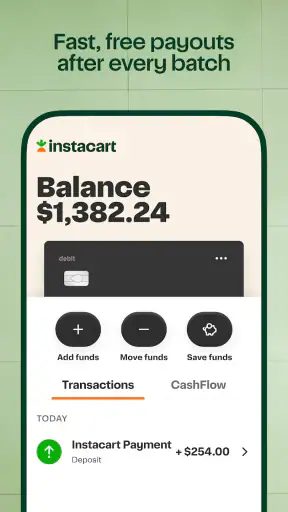
The strongest reason to try it is convenience. A shopper who wants a dedicated debit card connected to work-related earnings may prefer having that activity separated from a personal checking account. In practice, that can make it easier to distinguish money earned from shopping work from household income, especially when reviewing spending after a busy week.
I would not install it expecting a complete replacement for a traditional bank. The app’s identity is narrower: it centers on discovering and using the debit card associated with Instacart Shopper. That narrow purpose can be a benefit because fewer unrelated banking tools may stand between the user and the task at hand. It can also feel limiting if you want a broad financial dashboard, extensive budgeting tools, or a single place for every account.
The app’s current version is 2026.8.2, and it requires Android 10 or later. That requirement is reasonable for many recent phones, but it immediately excludes older devices that still handle basic finance apps well. Anyone using an aging handset should check the operating system before planning a switch, because the card itself may be appealing while the phone is simply incompatible.
What speed means here
For this kind of app, perceived speed is less about animation and more about how quickly I can get from opening the app to understanding what is available. A finance tool earns trust when its main purpose is easy to find and when routine checks do not feel like a maze. Instacart Shopper Rewards benefits from having a focused role, but users should still approach it as a companion to the shopper experience rather than as a universal financial command center.
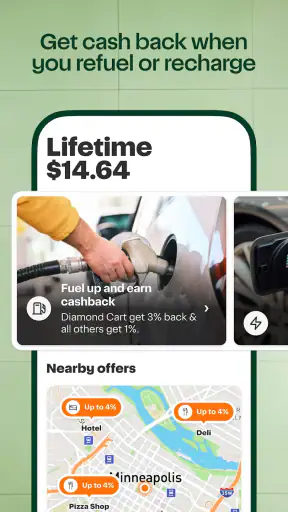
A realistic scenario is a shopper finishing a shift and wanting to keep work-related funds distinct from personal spending. Instead of mixing everything into a regular bank account, the user can treat the debit card as a separate spending lane. That separation is useful for fuel, meals while working, or other costs the shopper deliberately wants to monitor. I find this workflow more practical than trying to reconstruct work spending later from one crowded account.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
There is a trade-off, though. Separation only helps if the user develops a habit of checking the right account before paying. Someone who already manages several cards may find another financial destination creates more mental overhead, not less. The app is therefore more attractive to shoppers seeking a dedicated card arrangement than to people who are trying to reduce the number of accounts they use.
When usage becomes demanding
Light use should be straightforward: open the app, review the card-related information, and decide whether it fits the next expense. Heavy use is a different matter. A shopper may check balances repeatedly during a long day, switch between the shopper workflow and the rewards app, and rely on the phone while moving between locations. In that situation, the value of the app depends on consistent access and clear recovery when something interrupts the session.
I would keep expectations practical. A focused finance app does not need to be packed with visual effects or large media files, so there is no obvious reason to treat it like a demanding game. The real pressure comes from repeated context switching, mobile connectivity, and the user’s need to make a quick decision. If the app is being used as a work companion, small delays or an unclear return path can feel more serious than they would in a casual banking check.
One useful habit is to review the card before starting a busy work period, rather than waiting until a payment is urgent. That turns the app into a preparation tool instead of an emergency tool. I would also avoid assuming that a card-focused app should replace a written spending plan. A quick note separating fuel, food, and personal purchases can make the information much more useful when the day is over.
Another non-obvious trade-off is privacy through separation. Keeping shopper-related money apart may simplify personal bookkeeping, but it also means the user must remember which account holds which funds. The arrangement is helpful when the separation is intentional; it is frustrating when it becomes one more place to search during checkout.
Stability and what recovery should look like
Reliability matters more than novelty in a finance app. I care less about discovering a clever interface than I do about being able to return to the same card information without confusion. Because the product is tied to a specific shopper use case, a stable routine is especially important: check the account, use the card when appropriate, and confirm the result afterward.
I would treat any interruption carefully. If a session ends unexpectedly, the sensible response is to reopen the app and verify the displayed information before attempting a payment again. That is a better habit than repeatedly tapping a payment action while uncertain about whether the first attempt completed. The app can be convenient, but no finance workflow should encourage guessing.
Recovery also includes the human side of account access. Before depending on the card for a workday, I would make sure I know which sign-in details and account information I normally use. That preparation is easy to overlook because the app looks specialized, yet it becomes important when a phone is replaced, a session expires, or the user is working somewhere with an unreliable connection.
The available public reception is encouraging without being definitive. The app holds a 4.3 average and has more than one hundred reviews, which gives a prospective user some evidence that others are using it successfully. I would still avoid treating the rating as a guarantee of flawless performance. Finance apps can feel excellent for one workflow and awkward for another, particularly when a user expects features outside the app’s central purpose.
Older phones, storage, and daily device limits
The Android requirement is one of the clearest practical filters. Android 10 is not the newest platform, but it is still a meaningful cutoff for people who keep phones for many years. If your device cannot run that version, this is not a question of tweaking settings or freeing storage; you would need a compatible device to use the app.
For supported phones, I would judge resource demands by the surrounding situation rather than by expecting dramatic hardware strain. The app belongs to finance, not entertainment, so the important device constraints are likely to be available system support, battery condition, and the reliability of the phone’s connection during work. A phone that is already struggling with many open apps may make any mobile finance workflow feel slower, even when the app itself is not demanding.
That leads to a practical setup tip: close unnecessary work apps before checking the card during a rushed moment, and keep the phone sufficiently charged before a long shift. This is not a special feature of Instacart Shopper Rewards; it is a sensible way to reduce avoidable friction when the device is being used as a work tool. I would also avoid testing a new financial routine for the first time when I am already standing at a checkout.
iPhone users should think about the same everyday constraints, even though the stated minimum operating system is for Android. The important decision is whether the app fits the device and workflow available to you, not whether the category label sounds appealing. Since the product is specifically connected with Instacart Shopper, the shopper context should guide the decision more than general interest in debit cards.
Who will get the most value
I see the best fit in a shopper who wants a clear boundary between work-related funds and personal banking. That person may appreciate a focused debit card experience, especially when ordinary bank statements make it difficult to review the money connected with delivery or shopping work. The app can also suit someone who prefers a dedicated spending lane rather than adding work activity to an existing everyday account.
It is less suitable for someone who wants a traditional bank replacement. If your priority is broad account management, sophisticated budgeting, or consolidating several financial products, a full-service banking app will probably be a better main tool. Instacart Shopper Rewards can still have a supporting role, but I would not choose it as the center of an entire financial system.
I would also hesitate if you dislike managing multiple accounts or cards. The separation that helps one user can create confusion for another. Before installing, ask yourself whether you will actually use the card as a deliberate work account. If the answer is no, the app may add another login and another balance without solving a real problem.
How it compares with ordinary alternatives
The usual alternative is a personal bank account with a standard debit card. That option is familiar and often easier for people who want all spending in one place. Its weakness is visibility: work-related income and expenses can disappear into the rest of the household activity. The Instacart Shopper Rewards approach is more specialized, so it may make that particular separation easier.
A second alternative is a prepaid or secondary debit card used informally for work expenses. That can provide separation, but it may not feel as connected to the shopper’s routine. The advantage here is the app’s specific relationship to Instacart Shopper. The disadvantage is that the usefulness depends on being part of that ecosystem; it is not an equally compelling choice for someone with no shopper-related need.
A third option is a budgeting app layered over a normal bank account. That gives more room for categories and long-term planning, but it requires the user to maintain the system and classify transactions consistently. Instacart Shopper Rewards is potentially simpler for the narrow card task, while a budgeting tool is stronger when the goal is a complete view of income, bills, savings, and spending habits.
My advice is to choose based on the problem you are solving. If the problem is “I need a separate card experience for shopper-related money,” this app makes sense to investigate. If the problem is “I need to understand my entire financial life,” I would start elsewhere and use this only if the dedicated card adds a clear benefit.
Small workflow choices that make a difference
I would begin by deciding what the card is for before making it part of daily life. A narrow rule, such as using it for workday spending or keeping shopper-related funds apart, is easier to follow than a vague intention to use it “sometimes.” Clear rules also make it easier to notice whether the app is genuinely helping after a couple of weeks.
Next, I would check the app before a shift rather than during the busiest part of it. That gives me time to confirm that the phone is supported, the account is accessible, and the card fits the planned spending. This preparation is more valuable than repeatedly opening the app in a hurry, because it turns reliability into something I can manage rather than something I only discover under pressure.
Finally, I would keep the regular bank app available as a reference instead of abandoning it immediately. The two tools serve different purposes: one can remain the broad financial home, while this one handles the shopper-oriented card workflow. That staged approach reduces the risk of moving too much of my financial routine before I know whether the separation actually improves it.
My performance verdict
Instacart Shopper Rewards is a focused finance app with a clear audience and a practical reason to exist. I like the idea of separating shopper-related card activity from personal banking, and the free price makes it easy to consider without turning the decision into a major financial commitment. The 4.3 average and growing install base provide a reasonable sign of interest, while the Everyone rating makes its intended audience broad.
My reservation is not about the concept; it is about fit. The app will not automatically simplify money management for everyone. Users who need a complete bank replacement, detailed budgeting, or fewer accounts may be happier with a conventional banking or budgeting alternative. People with older Android phones also need to account for the Android 10 minimum before making plans.
For an Instacart shopper who wants a dedicated debit card workflow and is willing to manage that separation deliberately, I would recommend giving it a fair try. I would approach it as a specialized work companion, prepare the device before a busy day, and keep a broader banking tool for broader needs. Used that way, the app feels more purposeful than a generic finance download and more useful than its brief store summary suggests.
Pros
- Rewards can add extra value to regular shopping activity.
- Clear progress tracking helps you monitor your available benefits.
- Useful for shoppers who already use Instacart frequently.
- Offers may make certain work-related purchases more worthwhile.
- The program can complement regular shopper earnings and incentives.
Cons
- Reward availability may vary by location, eligibility, and account status.
- Some benefits may require meeting specific activity or spending conditions.
- Terms and reward values can change without much notice.
- Not every shopper will earn enough to make rewards significant.
- Benefits may have expiration dates or usage restrictions.
FAQs for Instacart Shopper Rewards
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program designed for eligible Instacart shoppers. Depending on your location, shopper status, and current program rules, it may provide access to discounts, savings, cashback opportunities, or other partner benefits. The exact rewards can change over time, so shoppers should review the terms inside the Instacart Shopper app before relying on a particular offer.
Who can use Instacart Shopper Rewards?
Availability generally depends on whether you are an active Instacart shopper and whether the program has been introduced in your market. Some benefits may require completing specific shopping activity, meeting eligibility requirements, or maintaining an account in good standing. Because participation rules can vary by region and may change, check the rewards section of the official shopper app for the most accurate information.
How do I access or redeem rewards?
Eligible shoppers can usually view available benefits through the Instacart Shopper app or a linked rewards page. Redemption instructions depend on the type of reward: some offers may apply automatically, while others require activating a promotion, using a code, or following a partner link. Always read the expiration date, usage limits, and additional conditions before completing a redemption.
Does Instacart Shopper Rewards cost money?
Access to a rewards program may not require a separate membership fee, but individual benefits can have restrictions or costs that are not immediately obvious. For example, a discount may apply only to selected products, services, or subscription plans, and taxes or delivery charges may still be excluded. Review each offer’s full terms carefully before making a purchase or sharing payment details.
Is Instacart Shopper Rewards available on Android and iPhone?
The rewards experience is primarily connected to the official Instacart Shopper platform, which is available for supported Android and iOS devices. Availability of the app, features, and specific rewards may depend on your country, operating-system version, account type, and current program rollout. Download only from the official Google Play Store or Apple App Store, and keep the app updated.

Instacart Shopper Rewards
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@branchapp.com, visit https://instacartcard-web.app.link/e/support-help-center, or review their http://www.branchapp.com/privacy.










